

The Central Bank of Sudan Director General of Strategic Planning: We Have a Strategic Plan and a Flexible Roadmap to Lead Banking and Financial Recovery
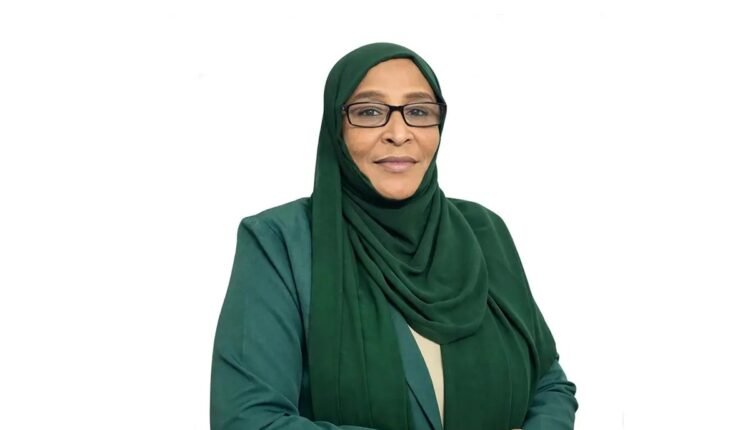
The Central Bank of Sudan (CBS) has launched its strategic plan for the 2026–2030 period—a critical juncture as Sudan seeks to rebuild its banking and financial sector following the severe challenges imposed by the war. The plan is anchored in a vision for an “inclusive and stable digital monetary and financial system.” It translates this vision into six strategic goals, 30 general objectives, and 150 initiatives and operational targets, all within a flexible framework designed to adapt to shifting economic and security conditions.
To explore the philosophy behind the plan, its core pillars, and its implications for both the public and the national economy, we submitted a series of questions to Ms. Tamador Mohammed Hussein, Director General of the General Administration for Strategic Planning and Corporate Communications. She kindly provided responses to *Sudanhorizon*; the details of the interview follow as below.
Interview: Editorial Team (ET)
Editorial Team: To begin, what is the Central Bank’s five-year strategic plan, and why was it introduced at this particular time?
Tamador: It is a five-year institutional roadmap aimed at driving the recovery and strategic transformation of the Central Bank. Its objectives include rebuilding confidence in the banking and financial systems, strengthening monetary and financial stability, and enhancing institutional and digital performance—all of which contribute to the recovery of the national economy and the achievement of sustainable development.
As for the timing, it is dictated by the circumstances themselves; The war has created significant challenges for the Sudanese economy, as well as for the banking and financial sectors. The recovery phase requires a scientific and methodical framework to rebuild the banking system, address mounting monetary and financial risks, and enhance the Central Bank’s capacity to lead economic recovery. Consequently, we have adopted a flexible approach that allows for the revision of policies and initiatives in response to shifting economic and security conditions, as well as available resources.
ET: What distinguishes this plan from conventional plans?
Tamador: It is distinguished by three key features:
– First, it integrates economic recovery, institutional reform, and digital transformation into a single, cohesive framework.
– Second, it is designed for monitoring and evaluation; strategic directions are translated into broad goals, specific initiatives, and operational objectives, the progress of which can be measured.
– Third, it employs a flexible, scenario-based planning approach. Rather than relying on rigid assumptions that fail to account for change, the plan allows for the adaptation of policies and initiatives as the situation evolves.
ET: What are the vision and mission that underpin this plan?
Tamador: Our vision is: “Towards an inclusive and stable digital monetary and financial system that contributes to rebuilding the national economy and achieving sustainable development.” This reflects our commitment to a more stable, efficient, and inclusive financial system—one that leverages modern technology, expands access to financial services, and strengthens the ability of banking institutions to support economic activity. Our mission is to “foster monetary and financial stability through effective policies, robust financial and banking institutions, an innovative digital infrastructure, and local and international partnerships that support recovery and development.” This mission underscores that stability is not achieved by monetary policy alone; it also requires strong institutions, a reliable technical infrastructure, and effective coordination among relevant stakeholders.
ET: What are the strategic objectives defined by the plan?
Tamador: The plan outlines six key strategic objectives that work in tandem to provide a comprehensive framework for recovery, reform, and development for the 2026–2030 period:
1. Achieving monetary and financial stability within the national economy.
2. Attaining institutional excellence by implementing best practices in governance, transparency, and accountability.
3. Strengthening and integrating domestic and external relations with regional and international financial institutions.
4. Achieving effective financial inclusion, ensuring that financial services are accessible to all segments of society.
5. Adopting and implementing digital transformation within the Central Bank and the banking sector to enhance efficiency and innovation.
6. Executing restructuring and reform programs for banks and financial institutions to ensure their resilience and effectiveness in supporting the banking system.
ET: How does the plan address inflation, and what is the target in this regard?
Tamador: Reducing inflation is a primary objective of the plan. It stipulates a gradual reduction of the inflation rate to stable, double-digit levels by the end of 2030, alongside a reduction in the growth rate of the money supply. It is a realistic target that takes into account the scale of current challenges, following a gradual path rather than relying on abrupt measures.
To achieve this, we are working to develop monetary tools to absorb excess liquidity, strengthen coordination between monetary and fiscal policy, and improve the management of liquidity and foreign reserves. It should be clearly understood that this target represents a strategic direction rather than a guaranteed inflation rate for any given year; it remains contingent upon economic and security developments, as well as the availability of resources.
ET: What about the exchange rate and the provision of foreign currency?
Tamador: The plan focuses on maintaining the stability of the local currency’s exchange rate through two parallel tracks: increasing foreign currency inflows and rationalizing demand for foreign currency. In this context, we are working to improve the management of foreign reserves, diversify their sources, and expand our network of correspondent banks.
The plan also includes establishing an early-warning mechanism to monitor fluctuations in the foreign exchange market, fostering regional cooperation, and exploring the settlement of commercial transactions in national currencies with key trading partners. Collectively, these measures aim to enhance our capacity to proactively manage foreign exchange market risks.
ET: How important is coordination with the Ministry of Finance in achieving these goals?
Tamador: Coordination between monetary and fiscal policy is a fundamental prerequisite for macroeconomic stability; neither can succeed in isolation from the other. The plan includes activating standing coordination committees between the Central Bank, the Ministry of Finance, and other relevant entities; standardizing the economic projections used in preparing budgets and monetary policy plans; establishing a shared monetary and financial database; and developing tools to assess the reciprocal impact of policies, curbing government borrowing from the Central Bank—in accordance with the Central Bank Laws —and improving the quality of economic statistics used for decision-making, thereby reducing inconsistencies between economic measures.
RT: How does the plan address the challenges the banking sector has faced due to the war? And what does bank restructuring entail?
Tamador: We are addressing these challenges through an integrated program for reforming financial institutions and restructuring banks. This includes strengthening banking supervision, gradually bolstering bank capital, updating legal and regulatory frameworks, ensuring business continuity, developing technical infrastructure and payment systems, and enhancing the protection of customer rights.
As for restructuring, it involves reassessing the status of banks and financial institutions and addressing weaknesses that affect their soundness, efficiency, and viability. This encompasses overseeing mergers, recapitalization, or—where necessary—orderly liquidation; managing non-performing loans through programs that account for the specific circumstances of each institution while maintaining confidence in the banking system; and redesigning business models to be more diversified, flexible, and responsive to the requirements of digital transformation and financial inclusion. The ultimate goal is for the banking sector to regain its role in financial intermediation and the financing of economic activities.
ET: And what about strengthening banking supervision?
Tamador: Supervision serves as the first line of defense for the soundness of the financial system. The plan includes updating the laws, regulations, and controls governing banking operations; enhancing oversight of systemically important banks; strengthening the supervisory role of the Central Bank of Sudan’s branches; completing the implementation of a risk-based supervision framework; and developing macroprudential supervision. We also place great importance on strengthening the governance of financial institutions and enhancing the proficiency of banking leadership in areas such as governance, risk management, and the handling of conflicts of interest.
ET: How will the plan work to restore public confidence in the banking system?
Tamador: Trust is built through actions, not statements. Therefore, our approach is based on four pillars: strengthening the soundness of financial institutions, improving the quality of banking services, developing regulatory frameworks for financial consumer protection, and increasing transparency in service delivery. The plan also includes enhancing communication channels with customers, improving the efficiency of complaint handling, developing digital services, and promoting financial and banking literacy. Restoring trust is a shared responsibility that requires banks to adhere to regulatory requirements and continuously improve the customer experience.
ET: Why is digital transformation a priority in the plan? And how do you protect customers from fraud?
Tamador: Digital transformation is a fundamental tool for increasing the efficiency of banking operations, accelerating transaction processing, strengthening information security, and expanding the reach of financial services. Our initiatives include developing digital infrastructure, improving payment systems, providing secure payment options for all segments of society, integrating national payment systems with regional and international networks, supporting innovation in financial technology (fintech), automating internal processes, expanding the use of digital signatures and electronic documentation, and leveraging artificial intelligence for data analysis and performance improvement.
As we expand our digital services, we place a strong emphasis on their security; cybersecurity is a critical component for building trust and ensuring the continuity of banking operations. Accordingly, the plan includes developing a cybersecurity framework aligned with international standards, conducting periodic penetration testing and risk assessments, strengthening identity and access management within the Bank, and implementing awareness campaigns regarding financial fraud and the security of electronic transactions.
ET: What is meant by financial inclusion, and how will it benefit the citizen?
Tamador: Financial inclusion refers to expanding access for individuals and enterprises to appropriate and secure financial and banking services that align with their needs and capabilities. The plan aims to enhance access to financial accounts and services, simplify account-opening requirements, expand the role of microfinance institutions, promote digital financial services, and support micro, small, and medium-sized enterprises (MSMEs).
For the people, this translates into easier financial transactions, broader access to financing, and greater participation in the economy for groups that previously struggled to access financial services. Furthermore, when implemented in conjunction with economic policies and productive initiatives, these measures help create a more favorable environment for productive sectors and the real economy—while acknowledging that achieving growth, production, and employment are goals that the Central Bank cannot accomplish alone.
Fifth: Governance, Institutional Development, and Partnerships
ET: How will institutional performance evolve within the Central Bank itself? And what is the role of regional and international partnerships?
Tamador: We begin from within; for the Bank to succeed in leading reform, it must itself serve as a model of governance. The plan includes updating organizational structures and procedural manuals, clarifying roles and responsibilities, enhancing transparency and accountability, and developing an integrated system for institutional and individual performance management. This system links performance indicators to the strategic plan and utilizes digital dashboards to monitor results. We also place special emphasis on human capital development and preparing future leaders, aligning training with performance evaluation and career progression, and establishing a system for knowledge management and institutional documentation.
Externally, regional and international relations serve as a pillar for recovery and reform. We are working to gradually restore formal ties with international financial institutions, actively engage in regional forums, secure technical assistance and capacity-building programs, and develop partnerships that support monetary and regulatory reforms. Furthermore, we are focused on improving the management of external debt—including the creation of a reliable and comprehensive database—and preparing our institutions to leverage relevant international initiatives in compliance with their specific terms and requirements.
ET: How was the plan developed? And did the relevant stakeholders within the Bank participate in the process?
Tamador: The plan was developed using a participatory institutional methodology. This process included reviewing and evaluating previous strategic plans, studying the experiences of various central banks, holding seminars and forums for staff, and conducting an analysis of the environment, the bank’s internal and external environments, gathering proposals from general departments and branches, and updating the institutional vision, mission, and values. The draft was subsequently reviewed and approved by the relevant management levels, and received the endorsement of the Central Bank’s Board of Directors prior to its launch. Through this methodology, strategic planning was aligned with the institutional reality and operational requirements.
ET: How will you address potential fluctuations in economic and security conditions during the implementation years?
Tamador: We have adopted flexible scenario-based planning, encompassing three scenarios: “Slow Recovery,” which assumes continued fragility in security and economic conditions alongside limited resources; “Balanced Recovery,” which assumes a gradual improvement in stability; and “Accelerated Growth,” based on a more rapid improvement in stability, the investment climate, resource inflows, and external support.
These scenarios are reviewed every six months to adjust initiatives and policies in line with the prevailing reality. This allows us to adapt our priorities to changing variables, rather than remaining committed to a single, rigid path regardless of shifting circumstances.
ET: And how will the success of the implementation be measured?
Tamadpr : Success will be measured through an integrated system of performance indicators linked to specific initiatives and operational objectives, digital dashboards to track progress, and periodic evaluations of both institutional and individual performance—in addition to the aforementioned semi-annual scenario reviews. We place great importance on distinguishing between two aspects: the completion of activities and initiatives, and their actual impact on monetary and financial stability, as well as the quality of banking services. Ultimately, the true measure of the plan’s success lies in the tangible impact experienced by the public and the economy.
ET: What are the key outcomes expected to be achieved by the plan by 2030?
Tamador : We aim to establish a stronger and more sustainable foundation for the monetary and financial system, enhance the efficiency of banking institutions, develop digital infrastructure, expand financial inclusion, improve governance and institutional performance, restore confidence in the banking system, strengthen risk management, and bolster regional and international financial relations. These are strategic objectives, the realization of which depends on effective implementation, the availability of resources, evolving general conditions, and coordination among the relevant institutions.
ET: What does this plan mean for the Sudanese citizen? Will conditions improve immediately?
Tamador: It means that the Central Bank has established a structured framework for its operations over the next five years, focusing on the stability of the monetary and financial system, banking reform, the development of digital services, expanded access to financial services, and enhanced consumer protection. The ultimate goal is to build a more efficient and stable financial system that serves both the individual and the national economy. In terms of daily life, the plan aims to make banking services more accessible by simplifying the account-opening process, advancing digital services, and improving channels for consumer protection and the resolution of complaints.
To be clear and honest:-
This plan is a medium-term strategic framework; it is not a promise of immediate results.
It addresses structural, monetary, and banking challenges through integrated policies and initiatives. The path toward improvement depends on economic and security conditions, the availability of resources, and the success of coordination between policies and the relevant institutions. We pledge to work systematically and to maintain transparency in monitoring progress.
ET: And a final word for the public?
Tamador : Our message is that banking and financial recovery require a gradual, integrated, and institutional approach—one founded on monetary and financial stability, reform and governance, digital transformation, expanded access to financial services, and the enhancement of transparency and cooperation. The 2026–2030 Strategic Plan serves as the framework that organizes these efforts, enabling us to track progress and remain accountable. We look forward to having citizens, banks, and all our partners join us on this journey.
Shortlink: https://sudanhorizon.com/?p=19689